Lease Buyout Bad Credit: Key Takeaways
- Bad creditdoesn’t automatically prevent a lease buyout. Many lenders consider factors beyond your credit score when reviewing a financing application
- The best lease buyout loan isn’t always the first one you find. Comparing multiple lenders may improve your approval chances and help you secure better loan terms
- Preparing before your lease ends can make a difference. Reviewing your credit, gathering financial documents, and understanding your payoff amount can strengthen your application
- A lease buyout may still be a smart financial move. If your vehicle has been reliable and its buyout price compares favorably to the current market, keeping it could cost less than replacing it
If your lease is coming to an end and your credit score isn’t where you’d like it to be, you may be wondering if buying your vehicle is even possible.
The good news? Bad creditdoesn’t automatically mean you’ll be denied a lease buyout loan.
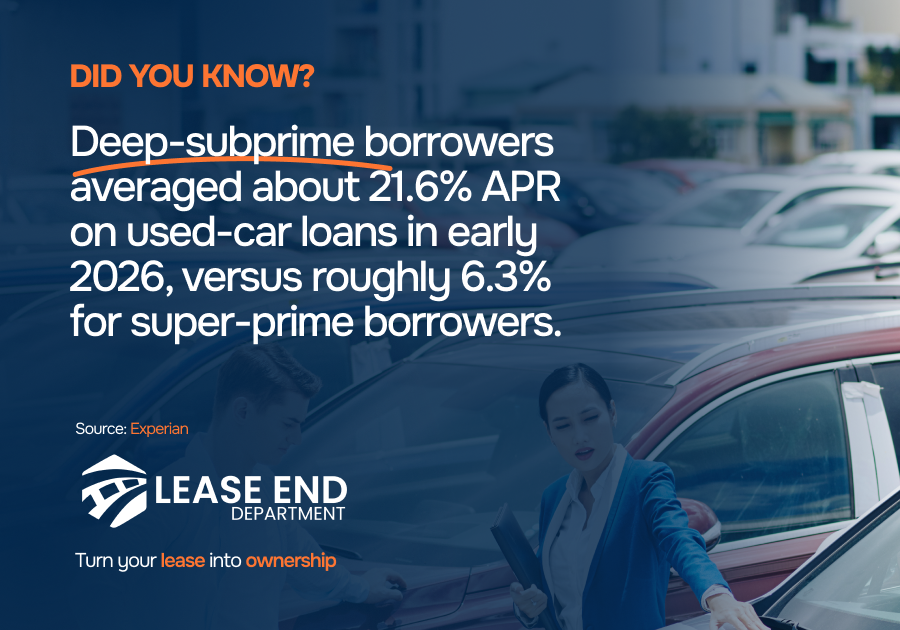
In fact, millions of drivers with less-than-perfect credit finance vehicles every year. Subprime borrowers accounted for more than 15% of all vehicle financing in late 2025, showing that lenders continue to approve auto loans for borrowers across a wide range of credit profiles.
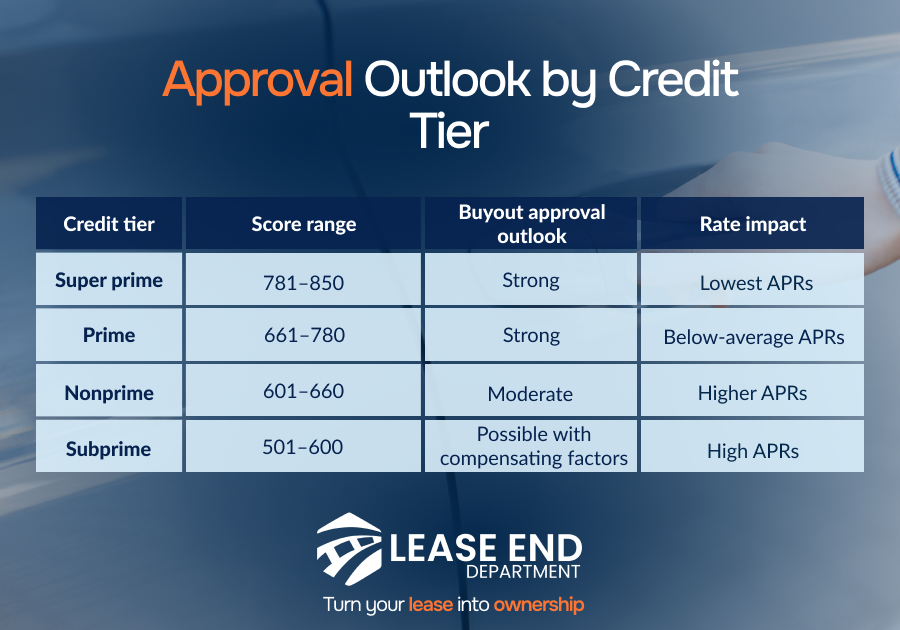
That doesn’t mean getting approved will be easy. A lower credit score can affect your interest rate, loan terms, and financing options. However, lenders often look beyond your credit score by considering factors such as your income, employment, existing debt, down payment, and even the value of the vehicle you’re buying.
If you’re considering a lease buyout with bad credit, understanding how the approval process works can help you prepare, compare lenders, and avoid unnecessary surprises.
In this guide, we’ll explain how lease buyout financing with bad credit works, what lenders typically evaluate, practical ways to improve your chances of approval, and when buying out your leased vehicle may still make financial sense.
Lease Buyout Bad Credit Doesn’t Always Mean “No”
Hearing the words “bad credit” can make it feel like a lease buyout is out of reach. But that’s one of the biggest misconceptions about auto financing. While your credit score is important, it isn’t the only factor lenders use when deciding whether to approve a lease buyout loan.
Every lender has its own approval criteria, which means one lender may decline your application while another may offer financing with different terms.
Why Every Lender Has Different Approval Requirements
There’s no universal credit score required for a lease buyout. Banks, credit unions, manufacturer finance companies, and online lenders all have their own lending guidelines and risk tolerance.
Some lenders prioritize long-term banking relationships, while others place greater emphasis on your current financial stability or the value of the vehicle you’re financing. That’s why comparing multiple lenders can often improve your chances of finding financing that fits your situation.
Your Credit Score Is Only One Piece of the Puzzle
When reviewing a lease buyout with bad credit, lenders often look at your overall financial picture, not just the number on your credit report.
They may consider factors such as:
- Income: Can you comfortably afford the monthly loan payment?
- Employment stability: A consistent work history may strengthen your application
- Debt-to-income ratio: Lenders compare your monthly debt obligations to your income to determine how much additional debt you can reasonably manage
- Down payment: Putting money down can reduce the amount you need to borrow and lower the lender’s risk
- Vehicle value: If your leased vehicle is worth close to or more than the buyout amount, lenders may view the loan more favorably
No single factor guarantees approval or denial. Looking at your finances gives lenders a better picture of your ability to repay the loan, which is why drivers with similar credit scores can receive very different financing offers.
How Lenders Evaluate a Lease Buyout Application
When you apply for a bad credit lease buyout loan, lenders want to answer one question: Can you realistically afford to repay the loan?
While your credit score is an important part of that decision, it isn’t the only thing they review.
Here’s what you should have in mind if there’s a lease buyout bad credit situation.
Your Credit History
Your credit report helps lenders understand how you’ve managed debt in the past. They’re typically looking for patterns rather than focusing on one isolated event.
For example, they may review:
- Your payment history
- Current credit balances
- Length of your credit history
- Recent credit inquiries
- Any bankruptcies, collections, or repossessions
A lower credit score may result in a higher interest rate, but it doesn’t automatically mean your application will be denied.
Your Financial Picture
Lenders also want to know whether your current finances support another monthly payment.
Common factors here include:
- Monthly income
- Employment stability
- Debt-to-income (DTI) ratio
- Housing expenses
- Existing loan and credit card payments
A stable income and manageable debt can strengthen your application, even if your credit score isn’t perfect.
Your Vehicle Matters, Too
Unlike many other types of loans, a lease buyout is secured by the vehicle you’repurchasing. Because of that, lenders often evaluate the car as carefully as they evaluate the borrower.
They may consider:
- The vehicle’s current market value
- Residual value
- Vehicle age
- Mileage
- Loan-to-value (LTV) ratio
For example, if your leased vehicle is worth $24,000 and your buyout amount is $22,500, the lender may view the loan as lower risk because the vehicle’s value supports the loan amount. On the other hand, if the buyout price is significantly higher than the vehicle’s market value, financing may become more difficult or more expensive.
Pro tip: Before applying for lease buyout with potentialbad credit, compare your payoff quote with your vehicle’s estimated market value. Knowing how much equity you may have can help you choose the right lender and better understand your financing options.
Your Lease Buyout Financing Options
If you have lease buyout bad credit, choosing where to apply can be just as important as whether you apply.
Many drivers assume they have only one financing option, usually the dealership or the manufacturer’s finance company. Several lenders may be willing to finance a lease buyout, and comparing them can improve your chances of approval while helping you secure a more competitive interest rate.
Not Every Lender Is Looking for the Same Borrower
Every lender has its own lending criteria and level of risk it’s willing to accept. One lender may decline your application, while another may approve it based on your income, employment history, or the value of your leased vehicle.
Rather than applying to just one lender, consider exploring several financing sources before deciding.
Where Should You Start?
Instead of applying randomly, begin with the lenders most likely to fit your financial situation.
| Financing source | Why it may be worth considering |
|---|---|
| Manufacturer finance company | May already have your lease history and payment record. |
| Credit union | Often offers competitive rates and may use more flexible underwriting than traditional banks. |
| Your current bank | An existing banking relationship may work in your favor. |
| Online auto lenders | Makes it easy to compare multiple financing offers without visiting several locations. |
The best lender isn’t always the one advertising the lowest interest rate. Approval requirements, loan terms, fees, and repayment flexibility all matter.
Compare More Than Just the Interest Rate
It’s easy to focus on APR, but that’s only one piece of the financing puzzle.
Before accepting any loan offer, compare:
- Monthly payment
- Total interest paid over the life of the loan
- Loan term
- Down payment requirements
- Origination or administrative fees
- Whether there are prepayment penalties
A loan with a slightly higher monthly payment may actually cost less overall if it has a shorter repayment term or fewer fees.
One Extra Step Could Save You Thousands
If your credit isn’t perfect, it can be tempting to accept the first approval you receive. However, spending an extra day comparing financing offers may lead to a lower interest rate, lower fees, or more manageable loan terms.
A lease buyout is a long-term financial commitment. Taking the time to compare lenders before signing the loan agreement can help you save money throughout the life of the loan while giving you greater confidence in your decision.
Put Yourself in the Best Position Before Applying
Getting approved for a car leasebuyout with bad creditisn’tjust about your credit score. The steps you take before submitting an application can influence your financing options, the interest rate you receive, and whether buying out your lease is the right financial move in the first place.
Start With the Things You Can Control
You can’t change your credit score overnight, but you can improve other parts of your application before approaching a lender.
A few simple steps include:
- Reviewing your credit report for errors
- Paying down revolving credit card balances, if possible
- Avoiding new credit applications before applying
- Saving for a down payment to reduce the loan amount
- Requesting an updated lease payoff quote
Even small improvements can strengthen your overall financial profile.
Be Ready Before You Apply
Having your paperwork organized can make the financing process faster and help lenders verify your information more efficiently.
Before submitting an application, gather:
- Proof of income
- Driver’s license
- Proof of insurance
- Your lease agreement or payoff quote
- Recent proof of residence, if requested
Being prepared won’t guarantee approval, but it can help avoid unnecessary delays.
Is Buying Out Your Lease Still the Right Financial Move?
Even if financing is available, it’s worth asking whether purchasing your leased vehicle makes financial sense.
A lease buyout is often worth considering when:
- The vehicle’s market value is higher than your buyout amount
- You’vemaintained the vehicle and know its complete history
- You plan to keep it for several more years
- Replacing it would cost more than expected
This is especially relevant in today’s market, where used vehicle prices remainhigher. If your buyout price compares favorably to similar vehicles for sale, keeping the car you already know may provide better long-term value than starting over with another used vehicle.
Avoid These Common Mistakes
Many drivers focus only on getting approved, but overlooking the bigger financial picture can become expensive.
Before signing a loan agreement, avoid these common pitfalls:
- Accepting the first financing offer without comparing lenders
- Waiting until the last few days of your lease to begin the process
- Looking only at the monthly payment instead of the total loan cost
- Forgetting to review the official payoff quote and purchase fees
- Assuming every lender evaluates applications the same way
Bad Credit Doesn’t Have to Be the End of Your Lease Buyout Journey
Having bad credit can make financing more challenging, but it doesn’t automatically mean you have to return the vehicle you’ve come to know and trust.
Many lenders consider more than just your credit score, and taking the time to compare financing options, review your payoff amount, and prepare your application can improve your chances of finding a solution that works for you.
Before finalplanning, try to look at the complete picture. Compare your lease buyout price with the vehicle’s current market value, understand the total cost of financing, and think about how long you plan to keep the car.
In many cases, buying out your lease can be a practical alternative to shopping for another vehicle, especially if your current one has been reliable and well maintained.
Navigating a lease buyout with bad credit can feel overwhelming, but you don’t have to figure it out on your own.
Lease End Department helps drivers:
- Review lease payoff quotes and purchase costs
- Explore lease buyout options
- Compare lenders and loan solutions
- Navigate the paperwork and ownership process from start to finish
Every driver’s financial situation is different, and the best lease buyout strategy depends on your goals, budget, and available financing options.
Lease Buyout Bad Credit: FAQs
Can you buy out a lease with bad credit?
Yes, it may be possible to buy out a lease with bad credit. While a lower credit score can affect your financing options and interest rate, many lenders consider other factors such as your income, employment history, debt-to-income ratio, and the value of the vehicle before making a lending decision.
Can I get a bad credit lease buyout loan?
Yes. Banks, credit unions, online lenders, and some manufacturer finance companies may offer a bad credit lease buyout loan. Approval requirements vary by lender, so comparing multiple financing options can improve your chances of finding a loan that fits your situation.
How does lease buyout financing with bad credit work?
Lease buyout financing with bad credit works much like a traditional auto loan. If you’re approved, the lender pays the lease buyout amount to the leasing company, and you repay the loan through monthly payments over an agreed-upon term. Your interest rate and loan terms will depend on factors such as your credit profile, income, and the vehicle’s value.
What credit score do you need for a car lease buyout with bad credit?
There isn’t a universal minimum credit score for a car lease buyout with bad credit. Every lender has its own approval criteria. Some may approve borrowers with lower credit scores if they have stable income, manageable debt, or a substantial down payment.
Will a down payment improve my chances of approval?
It can. A larger down payment reduces the amount you need to borrow, which may lower the lender’s risk. In some cases, it can also help you qualify for better loan terms or a lower monthly payment.
Can a cosigner help me finance a lease buyout?
Yes. Adding a qualified cosigner with stronger credit may improve your chances of approval and could help you qualify for a lower interest rate. Keep in mind that a cosigner is equally responsible for repaying the loan.
Is buying out my lease worth it if I have bad credit?
It depends on your financial situation and the value of your vehicle. If your lease buyout price is competitive, you’ve maintained the vehicle well, and you plan to keep it for several years, buying out your lease may still make financial sense, even with bad credit.